TPEx Taiwan Treasury Benchmark Index ()
TPEx Taiwan Treasury Benchmark Index
-
-
Time
I. Index name
Full name: TPEx Taiwan Treasury Benchmark Index
II. Ground Rules
(1) Index calculation method
Index algorithm:
Step 1: Calculate index base value on the index launch date
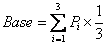
Step 2: Calculate the index on day t

The index is set at 1000 on its launch date.
where
 = Bond number in the index
 = The latest trading price (after-tax dirty price) of the constituent
 = Divisor, representing index base value
(2) Constituent selection criteria
Latest issued 5-year, 10-year and 20-year central government bonds (limited to Type A government bonds).
(3) Constituent adjustment
When a newly issued 5-year, 10-year, or 20-year central government bond is listed on TPEx, it will be added to the index on its third trading day. At the same time, the older bond of the same maturity that was previously included in the index will be removed.
For example:
- The 10-year central government bond A12110 was listed on TPEx on October 5, 2023.
- On October 11, 2023 (the third trading day after listing), A12110 was added to the index.
- The previously included 10-year bond A12107 was then removed from the index.
Index calculation in the event of constituent adjustment:
Total market value of constituents at closing before adjustment on the day preceding adjustment
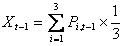
Total market value of constituents at closing after adjustment on the day preceding adjustment
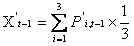
Index base value after constituent adjustment:

Index calculation after constituent adjustment:

where
= Bond number in the index
 = The day on which constituents are adjusted
 = The closing price (after-tax dirty price) of constituent before
adjustment on the day preceding adjustment
 = The closing price (after-tax dirty price) of constituent after
adjustment on the day preceding adjustment
= The latest trading price (after-tax dirty price) of the constituent
 = Divisor, representing index base value
(4) Sources of prices for index compilation
Sources of prices used for index compilation during trading hours are, in sequence, as follows:
- Transaction prices — The first choice is the actual transaction prices that are openly quoted in the Electronic Bond Trading System.
- Previous day’s last price — If no transaction occurs on the current trading day, the most recent closing price from the previous day is used instead.
For the daily report, the sources of prices used for index compilation, in sequence, are as follows:
- Transaction prices — The final transaction price of the day for publicly quoted transactions executed through the Electronic Bond Trading System.
- Mid quotes — If no transaction price is available, the system uses the midpoint of the final two-way public quotation with a bid-ask spread of no more than 10 bps through the Electronic Bond Trading System.
- Average transaction price — If neither of the above is available, the average transaction price from the Electronic Bond Trading System is used.
- Previous day’s price — As a final fallback, the price used for the index on the previous business day is applied.
An “Public Quotation” is a quote in the Electronic Bond Trading System that is visible to at least 90% potential counterparties (bond dealers). Because so many participants can trade at this level, it is considered a reliable, generally executable market price that is difficult for any single party to manipulate.
(5) Index disclosure frequency
- The index is updated every five seconds during trading hours, which run daily from 9:00 to 13:30.
- The daily report discloses the price of each central government bond included in the index calculation, along with any changes in the sample that occurred that day.