Taiwan Government Bond Index ()
I. Index name
Full Name: Taiwan Government Bond Index
II. Ground Rules
(1) Index calculation method
Index algorithm:
Step 1: Calculate index base value on the index launch date
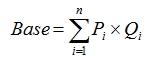
Step 2: Calculate index on day t
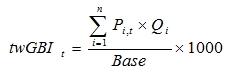
The index is set at 1000 on its launch date
where:
Pi= Price of series i government bond (The Price Index is calculated using clean prices [excluding accrued interest], while the Total Return Index is calculated using dirty prices [including accrued interest].)
Qi= Principal amount outstanding of series i bond (face amount outstanding ÷100)
Base = Divisor, representing index base value
(2) Constituent selection criteria
- Central government bonds that repay principal in a single payment at maturity (excluding local government bonds and exchangeable corporate bonds).
- Time to maturity is longer than one year.
(3) Constituent adjustment
Newly issued central government bonds are added to the index and bonds with one year or less to maturity are removed from index. Index calculation in the event of constituent adjustment
Assuming the weighted market value before adjustment is:Xt-1
Assuming the weighted market value after adjustment is:X’t-1
Weighted total market value on new start date: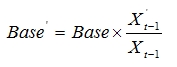
Index calculation starting the next day: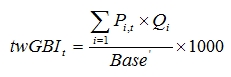
where
Pi=Price of series i government bond (price index uses clean prices, total return index uses dirty prices)
Qi=Principal amount outstanding of series i bond (face amount outstanding ÷100)
Base = Divisor, representing index base value
(4) Price Sources for Index Compilation
The sources of prices used for index compilation are applied in the following order:
- Transaction prices: The final transaction price of the day for publicly quoted transactions executed through the Computerized Negotiation System.
- Mid quotes: The midpoint of the final two-way public quotation with a bid-ask spread of no more than 10 bps through the Computerized Negotiation System.
- Dealer Estimates: The closing reference prices provided by government bond dealers.
- Previous day’s Price: The price used for the index on the previous business day.
Notes:
Public Quotations refer to quotes on the Electronic Bond Trading System (EBTS) where the number of quoting participants reaches 90% or more of all system participants. Consequently, Public Quotations are regarded as prices at which transactions can be universally executed in the market and are not easily manipulated by specific individuals. Furthermore, the transaction prices from Public Quotations are considered the most authoritative and credible bond trading prices in the market.
(5) Index disclosure frequency
The index is calculated and disclosed once after market closing each day. Also being disclosed daily are the prices of government bonds used for index calculation, daily changes to constituents, total market price of constituents for the day and the index base value (Base) for the day.