The TPEx-BOC Offshore RMB Bond Index is a market value weighted bond index in which constituents are selected from the TPEx-listed Formosa bonds ranked by their issue size and in consideration of their tenor and issuer. The index is designed to illustrate the overall performance of the TPEx Formosa Bond Market.
1. Selection of Constituents
1.1 Eligibility
The constituents of the TPEx-BOC RMB Bond Index are selected from Formosa bonds listed on TPEx and with tenor longer than six months (inclusive) and less than ten years (inclusive).
1.2 Prices of Constituents Used for Index Calculation
The RMB-denominated TPEx-BOC Offshore RMB Bond Index is calculated directly from the prices of its constituent bonds (in RMB).
1.3 Constituent Selection Criteria
- (1) Issue size
The bond must have an outstanding principal amount of RMB 500 million or more. - (2) Credit rating
The bond issuer must have a credit rating of A+, A, or A- from Standard & Poor’s, or A1, A2 or A3 from Moody’s. If the issuer is rated by both Standard & Poor's and Moody’s, the Standard & Poor’s rating will prevail for constituent selection. - (3) Principal repayment and interest accrual
The bond must bear a fixed interest rate and repay the principal in a single payment at maturity. Zero-coupon bonds and bonds with warrants are not eligible for inclusion.
2. Index Calculation Method
2.1 Calculation frequency
The TPEx-BOC Offshore RMB Bond Index is calculated in real time and published every five seconds during the TPEx trading hours based on the latest trading prices of constituents. A closing index will be calculated after the market closing each day.
2.2 Sources of prices
The sources of prices used for index calculation are in sequence:
- (1) The real-time transaction prices from the TPEx international bond system or as reported by securities firms.
- (2) Fair value (dirty price) provided by TPEx.
The TPEx fair values are derived from the sum of discounted cashflows based on the zero-coupon yield curves obtained via bootstrapping from the Formosa bonds yield curves constructed using the quotes given by bond dealers.
2.3 Index algorithm
- (1) Calculation formula

where
Pi,tis the dirty price of constituent i per $1 face value at time t
Qi,tis the principal amount outstanding of constituent i at time t
Baseis the index base value determined by the total market value of all constituents on the index base date
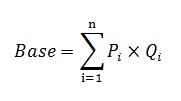
- (2) Base adjustment
When the index calculation is disrupted due to constituent adjustment and interest payment, its base is adjusted as follows:
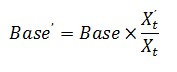
Xt is the total market value before adjustment
X'tis the total market value after adjustment
Base’is the index base value on a new base date
If the prices of the constituents stay unchanged, the index will stay unchanged when there is a constituent adjustment or interest payment:

3. Constituent Review and Rebalancing
A monthly constituent review shall be conducted on the last business day of each month. Any eligible bond that has been issued but has not yet been included in the TPEx–BOC Offshore RMB Bond Index shall be added to the Index, provided that it satisfies the constituent selection criteria. At the same time, any constituent bond with a remaining term to maturity of less than six months as of the following month shall be removed from the Index. The additions and deletions resulting from the monthly constituent review shall become effective on the first business day of the following month.
Any newly issued Formosa Bond that satisfies the constituent selection criteria of the TPEx–BOC Offshore RMB Bond Index shall be included in the Index as a constituent on its issuance date.
A constituent bond shall be removed from the Index immediately if:
- the issuer's credit rating is downgraded such that it no longer satisfies the constituent selection criteria; or
- the bond's outstanding principal amount falls below RMB 500 million.
If trading in a constituent bond is suspended by TPEx, the bond may remain in the Index during the suspension period. In such cases, the fair value published daily by TPEx shall be used for index calculation purposes. The suspended bond shall remain as an Index constituent until the next scheduled constituent review, at which time it shall be removed from the Index.
A constituent bond that has been removed from the Index due to a trading suspension may be re-included in the Index following the resumption of trading, provided that it satisfies the constituent selection criteria during the constituent review conducted in the month in which trading resumes. The re-inclusion shall become effective on the first business day of the following month.